Achieve Your Financial Dreams: Master Short-Term Savings Goals: Master Short-Term Savings Goals by 2026
In a world brimming with instant gratification, the ability to set and achieve short-term savings goals stands as a cornerstone of financial stability and future prosperity. Whether you’re dreaming of a down payment on a new car, a memorable vacation, clearing high-interest debt, or building a robust emergency fund, having a clear roadmap to reach these financial milestones within 6 to 12 months by 2026 is not just aspirational – it’s entirely achievable. This comprehensive guide will equip you with the strategies, tools, and mindset necessary to turn your short-term savings goals into tangible realities, empowering you to take control of your financial destiny.
Many people find themselves stuck in a cycle of wanting to save but struggling to make significant progress. The key often lies in understanding the nuances of short-term financial planning, setting realistic expectations, and implementing consistent, effective strategies. We’ll delve into everything from crafting an airtight budget to identifying hidden savings opportunities and even boosting your income. By the end of this article, you’ll have a clear, actionable plan to tackle your short-term savings goals with confidence and precision.
Defining Your Short-Term Savings Goals: Clarity is Power
Before you can embark on any savings journey, you must first clearly define your destination. What exactly are your short-term savings goals? Are they specific, measurable, achievable, relevant, and time-bound (SMART)? This framework is crucial for success. Instead of vaguely saying, “I want to save money,” articulate it as, “I want to save $5,000 for a down payment on a new car within the next 10 months.”
What Constitutes a Short-Term Goal?
- Timeframe: Typically 6 to 12 months, though some might extend it to 18-24 months. For the purpose of this article, we’ll focus on the 6-12 month horizon to ensure rapid progress and maintain motivation.
- Purpose: These goals are usually for specific, tangible items or experiences.
- Urgency: There’s often a clear reason why you want to achieve these goals relatively quickly.
Examples of Common Short-Term Savings Goals:
- Emergency Fund: Building 3-6 months of living expenses.
- Vacation: Saving for a specific trip, including flights, accommodation, and activities.
- Large Purchase: A new appliance, furniture, or a down payment on a vehicle.
- Debt Repayment: Tackling high-interest credit card debt or a personal loan.
- Education/Skill Development: Funding a short course or certification.
- Home Repairs: Saving for essential maintenance or minor renovations.
Once you’ve identified your goal, write it down. Make it visible. This act of commitment significantly increases your chances of success. Break down the total amount needed by the number of months you have. For example, if you need $5,000 in 10 months, you need to save $500 per month. This monthly target becomes your guiding star.
The Foundation: Crafting an Ironclad Budget for Your Short-Term Savings Goals
A budget is not about restriction; it’s about empowerment. It’s your financial GPS, showing you exactly where your money is going and where you can redirect it to achieve your short-term savings goals. Without a clear understanding of your income and expenses, saving effectively is like trying to hit a moving target blindfolded.
Step 1: Track Your Income and Expenses
For at least one month, meticulously track every dollar that comes in and every dollar that goes out. Use an app, a spreadsheet, or even a notebook. The goal here is awareness, not judgment. You might be surprised at where your money is actually going.
Step 2: Categorize Your Spending
Group your expenses into categories like housing, transportation, food, entertainment, utilities, and debt payments. This helps you see patterns and identify areas for potential cuts.
Step 3: Distinguish Between Needs and Wants
This is where the magic happens for short-term savings goals. Needs are essential for survival (shelter, food, basic utilities). Wants are everything else (dining out, subscriptions, new clothes, entertainment). While wants contribute to quality of life, they are often the first place to look when trying to accelerate savings.
Step 4: Create a Realistic Budget
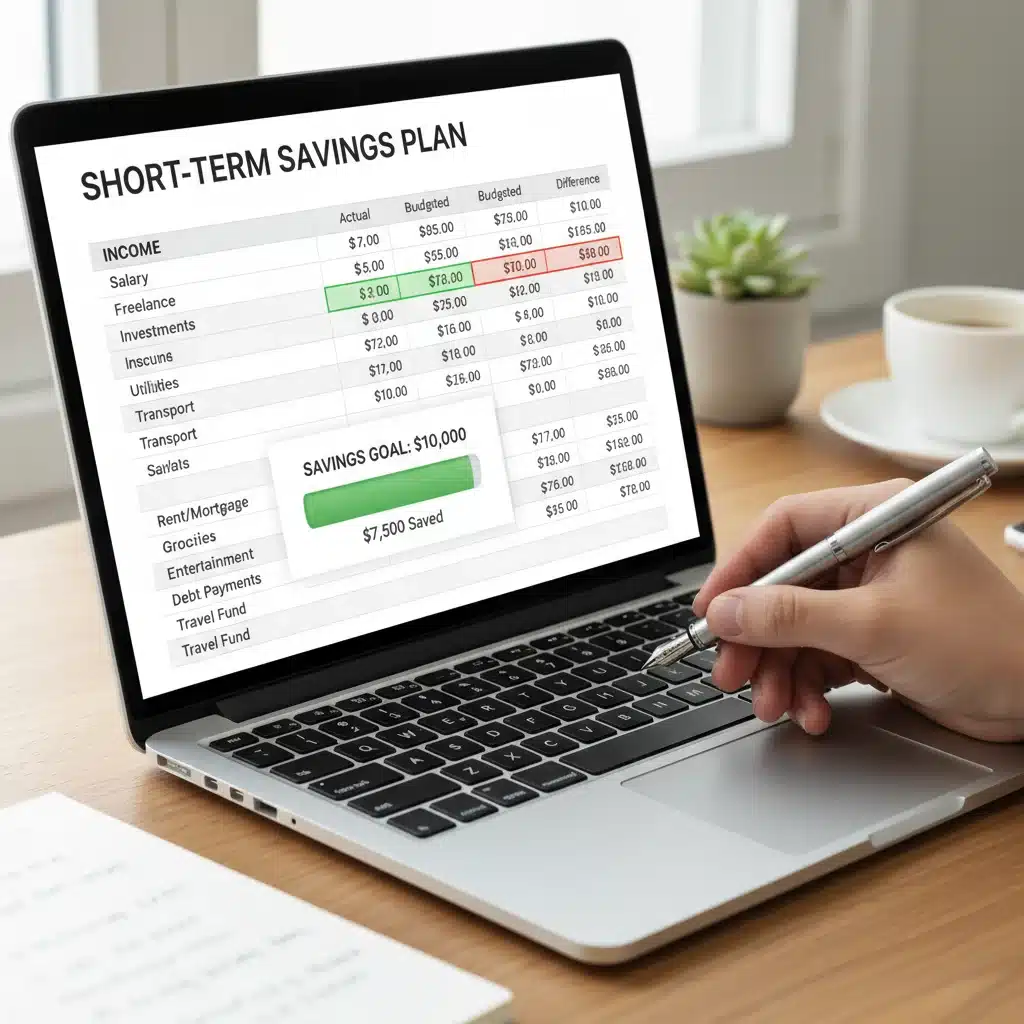
Allocate specific amounts to each category. Be honest with yourself. An overly restrictive budget is unsustainable. Many people find the 50/30/20 rule helpful: 50% for needs, 30% for wants, and 20% for savings and debt repayment. Adjust these percentages to prioritize your short-term savings goals.
Strategic Expense Reduction: Freeing Up Funds for Your Goals
Once your budget is in place, the next step is to actively find ways to reduce your expenses. This isn’t about deprivation; it’s about conscious choices that align with your short-term savings goals.
Identify and Cut Unnecessary Spending
- Subscriptions: Review all recurring subscriptions (streaming services, gym memberships, apps). Do you use them all? Can you pause or cancel some temporarily?
- Dining Out: This is often a major money sink. Commit to cooking more meals at home. Pack your lunch instead of buying it.
- Impulse Buys: Implement a ’24-hour rule’ for non-essential purchases. If you still want it after 24 hours, reconsider.
- Coffee Habits: Brewing coffee at home instead of daily cafe visits can save hundreds over several months.
Optimize Essential Expenses
- Groceries: Plan meals, make a shopping list, and stick to it. Buy generics, look for sales, and avoid shopping when hungry.
- Utilities: Be mindful of energy consumption. Unplug electronics, turn off lights, and adjust your thermostat.
- Transportation: Carpool, use public transport, or walk/bike when possible. Review your car insurance for better rates.
- Negotiate Bills: Call your internet, cable, and even insurance providers. Often, you can negotiate lower rates or better packages.
Every dollar saved from these areas can be directly allocated to your short-term savings goals. Think of it as giving yourself a raise dedicated solely to your financial aspirations.
Boosting Your Income: Accelerating Your Short-Term Savings
While cutting expenses is vital, increasing your income can dramatically accelerate your progress towards short-term savings goals. This doesn’t necessarily mean getting a new job, but rather exploring avenues for additional earnings.
Side Hustles and Freelancing
The gig economy offers numerous opportunities to earn extra money:
- Freelance Work: Offer skills like writing, graphic design, web development, or social media management on platforms like Upwork or Fiverr.
- Delivery Services: Drive for Uber Eats, DoorDash, or Instacart during your free time.
- Pet Sitting/Dog Walking: If you love animals, this can be a flexible way to earn cash.
- Online Tutoring: Share your knowledge in a subject you excel at.
- Selling Crafts/Products: If you have a creative hobby, consider selling your creations online or at local markets.
Selling Unused Items
Decluttering your home can also be a lucrative endeavor. Sell clothes, electronics, furniture, or collectibles on platforms like eBay, Facebook Marketplace, or local consignment shops. Not only do you get extra cash for your short-term savings goals, but you also create more living space.
Asking for a Raise or Taking on More Hours
If applicable, consider discussing a raise with your employer or volunteering for overtime. Even a small increase in your regular income can make a significant difference over several months.
Automation and Dedicated Accounts: The Path to Consistent Savings
One of the most powerful strategies for achieving short-term savings goals is to automate your savings. This removes the temptation to spend the money and ensures consistent progress.
Set Up Automatic Transfers
Schedule a recurring transfer from your checking account to a dedicated savings account each payday. Treat this transfer like any other bill – it’s non-negotiable. Even small, consistent amounts add up quickly.
Use a High-Yield Savings Account (HYSA)
For your short-term savings goals, consider parking your money in a high-yield savings account. These accounts offer significantly higher interest rates than traditional savings accounts, meaning your money works harder for you. Ensure the account is easily accessible when you need it but separate enough from your daily checking account to avoid impulsive spending.
Open Separate Savings Accounts for Each Goal
If you have multiple short-term savings goals, consider opening separate savings accounts for each. Label them clearly (e.g., “Car Down Payment,” “Vacation Fund,” “Emergency Buffer”). This psychological trick helps you visualize your progress towards each specific goal and keeps you motivated.
Psychological Hacks to Stay Motivated
Saving money, especially for short-term savings goals, requires discipline and sustained motivation. Here are some psychological strategies to keep you on track:
Visualize Your Success
Regularly picture yourself achieving your goal. If it’s a vacation, imagine yourself on the beach. If it’s a car, see yourself driving it. This positive reinforcement can be incredibly powerful.
Track Your Progress
Seeing your savings grow is a huge motivator. Use a spreadsheet, a savings tracker app, or even a physical chart. Celebrate small milestones along the way. Reaching 25%, 50%, or 75% of your goal deserves recognition.
Reward Yourself (Sensibly)
When you hit a significant milestone, give yourself a small, non-financial reward. This could be a guilt-free movie night, a long bath, or an afternoon dedicated to a hobby. Avoid rewards that derail your savings progress.
Find an Accountability Partner
Share your short-term savings goals with a trusted friend, family member, or partner. Regularly check in with each other to discuss progress, challenges, and successes. Knowing someone else is aware of your goals can provide an extra layer of motivation.
Understand the ‘Why’ Behind Your Goals
Connect your financial goal to a deeper personal value. Why is this specific short-term savings goal important to you? Is it security, freedom, experience, or growth? Reminding yourself of this deeper ‘why’ will help you stay committed when challenges arise.
Addressing Common Challenges and Pitfalls
No savings journey is without its bumps. Anticipating and preparing for common challenges can help you navigate them effectively and keep your short-term savings goals on track.
Unexpected Expenses
Life happens. A car repair, a medical bill, or an urgent home repair can suddenly emerge. This is where your emergency fund (which can also be a short-term goal) proves invaluable. If you don’t have one yet, consider making a small emergency buffer part of your current short-term savings goals.
Loss of Motivation
It’s natural for enthusiasm to wane. Revisit your ‘why,’ review your progress, and perhaps adjust your budget slightly if it’s too restrictive. Sometimes, a small, guilt-free treat can re-energize you.
Lifestyle Inflation
As your income potentially increases, resist the urge to immediately upgrade your lifestyle. This phenomenon, known as lifestyle inflation, can quickly derail your short-term savings goals. Instead, direct any extra income towards your savings first.
Peer Pressure
It can be tough to say no to social outings or expensive activities when friends are participating. Be honest about your financial goals. True friends will understand and support your efforts, perhaps even suggesting more budget-friendly alternatives.
Information Overload
The internet is full of financial advice. Stick to a few core strategies that resonate with you and avoid constantly jumping between different methods. Consistency is more important than perfection.
Advanced Strategies for Rapid Short-Term Savings
For those looking to supercharge their short-term savings goals, consider these more aggressive strategies:
The No-Spend Challenge
Commit to a period (a weekend, a week, or even a month) where you only spend money on absolute necessities. This forces you to get creative with existing resources and highlights areas of unnecessary spending.
Cash-Only Budgeting
For categories like groceries, entertainment, or personal spending, withdraw a set amount of cash at the beginning of the week or month. Once the cash is gone, you stop spending in that category. This physical limitation can be very effective.
Debt Snowball/Avalanche Method
If one of your short-term savings goals is debt repayment, these methods can accelerate the process. The snowball method focuses on paying off the smallest debt first for psychological wins, while the avalanche method targets the highest interest debt first to save money on interest.
Temporary Austerity Measures
For a limited time, you might adopt more extreme measures. This could mean temporarily cutting out all non-essential spending, cancelling all subscriptions, or even taking on a second job for a few months. These are not long-term sustainable, but for a short, intense push towards a goal, they can be highly effective.
Review and Adjust Regularly
Your budget and savings plan are not static. Life changes, and so should your financial strategy. Review your progress monthly. Are you on track? Do you need to adjust your spending or find new income streams? Flexibility is key to long-term success with short-term savings goals.
Conclusion: Your Path to Financial Achievement by 2026
Achieving your short-term savings goals within 6 to 12 months by 2026 is an ambitious yet entirely attainable endeavor. It requires a combination of clear goal setting, diligent budgeting, strategic expense reduction, and, where possible, income augmentation. By implementing the strategies outlined in this guide – from defining SMART goals and tracking every dollar to automating your savings and staying motivated – you are not just saving money; you are building a foundation of financial discipline and empowering yourself to make your dreams a reality.
Remember, every small step forward is progress. Don’t get discouraged by setbacks; simply learn from them and recommit to your plan. With focus, consistency, and the right approach, your short-term savings goals are well within reach. Start today, and witness the incredible power of intentional financial planning transform your future.