Achieving 7% Annual Investment Returns: Strategies for Today’s Economy
Achieving 7% Annual Investment Returns: Strategies for Today’s Economy
In the dynamic world of finance, aspiring to achieve a consistent 7% annual return on your investments is a goal that many savvy investors share. While it might sound ambitious in some market conditions, with a well-thought-out strategy, diligent execution, and an understanding of the current economic climate, this target is indeed attainable. This comprehensive guide will delve into the core principles and advanced strategies necessary to optimize your investment portfolio, navigate market fluctuations, and position yourself for consistent growth, ultimately helping you achieve that coveted 7% annual return.
The journey to a 7% annual return is not a straight line; it involves continuous learning, adaptation, and a disciplined approach to investing. We will explore various investment vehicles, risk management techniques, and the importance of diversification, all tailored to help you build a robust portfolio capable of weathering economic storms and capitalizing on opportunities. Understanding the current economic landscape is paramount, as inflation rates, interest rate policies, and geopolitical events significantly influence market performance and, consequently, your potential returns.
Before we dive into specific strategies, it’s crucial to establish a foundational understanding of what a 7% annual return truly means in the context of investing. Historically, the average annual return of the S&P 500 has been around 10-12% over long periods, though this includes significant fluctuations. A target of 7% annual return is often considered a realistic and healthy goal, especially when factoring in a balanced approach to risk and return. It allows for substantial wealth accumulation over time, thanks to the power of compounding, without necessarily exposing your portfolio to excessive volatility.
Understanding the Current Economic Climate and Its Impact on Your 7% Annual Return Goal
The global economy is a complex ecosystem, constantly influenced by a myriad of factors. To consistently achieve a 7% annual return, it’s vital to have a finger on the pulse of current economic conditions. High inflation, rising interest rates, supply chain disruptions, and geopolitical tensions are all elements that can affect investment performance. For instance, in an inflationary environment, certain assets like real estate, commodities, and inflation-protected securities might perform better, offering a hedge against the erosion of purchasing power. Conversely, growth stocks might face headwinds as higher interest rates increase borrowing costs and discount future earnings more aggressively.
Interest rates, set by central banks, play a crucial role. When rates rise, bonds typically lose value, but new bonds offer higher yields, which can be attractive for income-seeking investors. Higher rates can also slow economic growth, impacting corporate earnings and stock market performance. Understanding these dynamics allows you to adjust your portfolio allocation strategically to maintain your pursuit of a 7% annual return. For example, during periods of rising rates, you might consider shorter-duration bonds or dividend-paying stocks that offer a more stable income stream.
Moreover, global economic growth forecasts and trade policies can influence the performance of international investments. Diversifying across different geographies and sectors can mitigate country-specific risks and potentially enhance your chances of achieving a consistent 7% annual return. Staying informed through reputable financial news sources, economic reports, and expert analyses is not just beneficial; it’s essential for making informed investment decisions that align with your 7% annual return objective.
Foundation of a Robust Portfolio: Diversification and Asset Allocation for a 7% Annual Return
The cornerstones of any successful investment strategy aimed at a 7% annual return are diversification and asset allocation. These principles are not merely buzzwords; they are critical tools for managing risk and optimizing returns across different market cycles.
The Power of Diversification
Diversification involves spreading your investments across various asset classes, industries, and geographical regions to reduce risk. The old adage, “Don’t put all your eggs in one basket,” perfectly encapsulates this concept. If one asset class or sector performs poorly, the impact on your overall portfolio is cushioned by the positive performance of others. For example, a diversified portfolio might include a mix of:
- Stocks: Large-cap, mid-cap, small-cap, domestic, international, growth, and value stocks.
- Bonds: Government bonds, corporate bonds, municipal bonds, and international bonds of varying durations and credit qualities.
- Real Estate: Direct ownership, Real Estate Investment Trusts (REITs).
- Commodities: Gold, silver, oil, agricultural products.
- Alternative Investments: Private equity, hedge funds (for accredited investors), peer-to-peer lending.
By diversifying, you aim to smooth out the volatility of your portfolio, making the path to a 7% annual return more stable and predictable. It’s about creating a portfolio where different assets perform well under different economic conditions, ensuring that your overall returns remain resilient.
Effective diversification isn’t just about the number of investments; it’s about investing in assets that have a low correlation with each other. This means that when one asset goes down, another might go up or remain stable, thus balancing the portfolio. Achieving a consistent 7% annual return often hinges on this strategic balancing act.
Strategic Asset Allocation
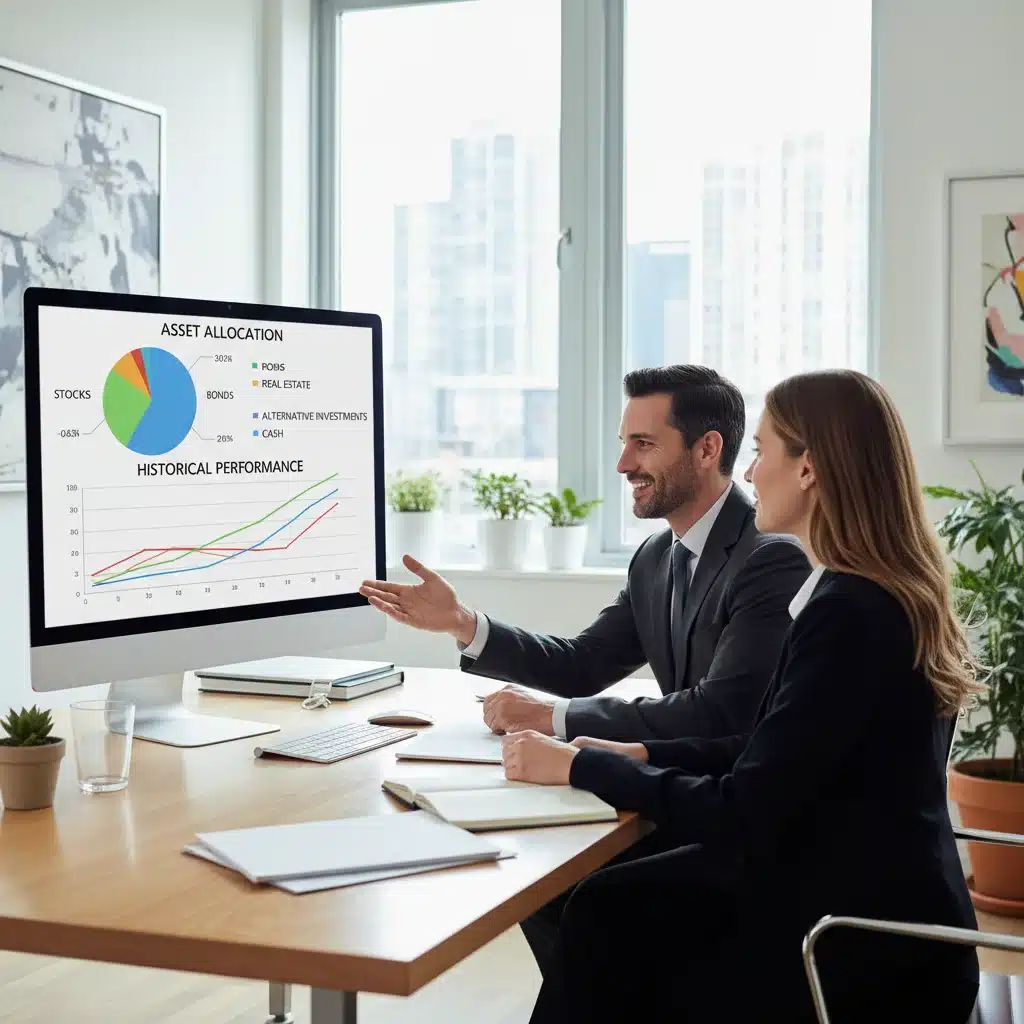
Asset allocation is the process of deciding how to divide your investment capital among different asset classes based on your risk tolerance, investment horizon, and financial goals. There is no one-size-fits-all asset allocation strategy; it must be personalized. However, for a target of 7% annual return, a common approach might involve a higher allocation to equities (stocks) for their growth potential, balanced with a healthy portion of fixed-income (bonds) for stability and income, and potentially a small allocation to alternatives for further diversification.
For example, a moderate investor aiming for a 7% annual return might consider an allocation like:
- 60-70% Equities: Offering growth potential.
- 20-30% Fixed Income: Providing stability and income.
- 5-10% Alternatives/Real Estate/Commodities: For enhanced diversification and inflation hedge.
This allocation is a starting point and should be regularly reviewed and rebalanced. Rebalancing involves adjusting your portfolio back to your target allocation when market movements cause it to drift. For instance, if stocks have performed exceptionally well, their percentage in your portfolio might exceed your target. Rebalancing would involve selling some stocks and buying more of the underperforming assets to restore your desired allocation. This disciplined approach helps in “buying low and selling high” over time, contributing significantly to achieving a consistent 7% annual return.
Investment Vehicles to Target a 7% Annual Return
To achieve a 7% annual return, you need to select investment vehicles that align with your risk profile and offer the potential for such returns. Here are some common options:
- Exchange-Traded Funds (ETFs) and Mutual Funds: These allow you to invest in a diversified basket of stocks, bonds, or other assets with a single purchase. They are excellent tools for achieving broad market exposure and diversification without having to pick individual securities. For example, an S&P 500 index ETF can provide exposure to the largest U.S. companies, historically yielding strong returns over the long term. Sector-specific ETFs or those focusing on international markets can further diversify your portfolio.
- Dividend Stocks: Companies that consistently pay dividends can provide a steady income stream that contributes to your 7% annual return. Reinvesting these dividends can significantly boost your returns through compounding. Look for companies with a strong history of dividend growth and stable earnings.
- Growth Stocks: These are stocks of companies expected to grow at an above-average rate compared to other stocks. While potentially more volatile, successful growth stocks can deliver substantial capital appreciation. However, they require thorough research and a higher risk tolerance.
- Bonds and Fixed Income: While individual bonds might not offer a 7% annual return on their own, a diversified bond portfolio can provide stability and income. High-yield corporate bonds or emerging market bonds can offer higher returns but come with increased risk. Bond ETFs can provide diversified exposure to various types of bonds.
- Real Estate: Investing in real estate, either directly or through REITs, can provide both income (from rent) and capital appreciation. REITs are particularly attractive for their liquidity and diversification benefits, offering exposure to various property types without the hassle of direct ownership.
- Alternative Investments: For those with a higher risk tolerance and sufficient capital, alternatives like private equity, venture capital, or even certain structured products might offer higher return potential, but often come with less liquidity and higher fees.
The key is to combine these vehicles judiciously, ensuring that your overall portfolio is aligned with your target of a 7% annual return while managing risk effectively.
Risk Management Strategies for a Stable 7% Annual Return
Risk is an inherent part of investing. The goal is not to eliminate risk entirely but to manage it intelligently to protect your capital and ensure a stable path toward your 7% annual return. Effective risk management involves several strategies:
- Understanding Your Risk Tolerance: Before making any investment, honestly assess how much risk you are comfortable taking. This will guide your asset allocation decisions. A higher risk tolerance might allow for a higher allocation to equities, while a lower tolerance might favor more conservative investments.
- Regular Portfolio Review and Rebalancing: As mentioned earlier, regularly reviewing your portfolio (e.g., quarterly or annually) and rebalancing it back to your target asset allocation is crucial. This ensures you’re not taking on unintended risk and helps you stay on track for a 7% annual return.
- Stop-Loss Orders: For individual stock investments, stop-loss orders can help limit potential losses by automatically selling a security if it drops to a certain price.
- Dollar-Cost Averaging: This strategy involves investing a fixed amount of money at regular intervals, regardless of market fluctuations. When prices are high, your fixed amount buys fewer shares; when prices are low, it buys more. Over time, this averages out your purchase price and reduces the risk of investing a large sum at an unfortunate market peak. This disciplined approach can significantly aid in achieving a consistent 7% annual return.
- Emergency Fund: Before investing, ensure you have an adequate emergency fund (typically 3-6 months of living expenses) in a liquid, easily accessible account. This prevents you from having to sell investments at an inopportune time to cover unexpected expenses, thus protecting your long-term growth trajectory towards a 7% annual return.
Behavioral Finance: The Psychological Aspect of Achieving a 7% Annual Return
While technical analysis and economic forecasts are vital, human psychology often plays a significant role in investment outcomes. Behavioral biases can lead to irrational decisions that derail your efforts to achieve a 7% annual return.
- Fear and Greed: These two powerful emotions often drive investors to make poor decisions. Fear can lead to selling during market downturns, locking in losses, while greed can lead to chasing high-flying stocks or taking on excessive risk. A disciplined approach, sticking to your investment plan, and avoiding emotional reactions are crucial.
- Confirmation Bias: This is the tendency to seek out information that confirms your existing beliefs and ignore information that contradicts them. It can lead to overlooking critical data that might suggest a change in strategy is needed.
- Herd Mentality: The tendency to follow the actions of a larger group, often without independent critical analysis. This can lead to buying into bubbles or selling during panics.
Being aware of these biases and actively working to mitigate their influence is as important as any financial strategy. A well-defined investment plan and a commitment to long-term goals can help you overcome these psychological pitfalls and stay focused on your 7% annual return target.
Leveraging Technology for Your 7% Annual Return Goal
In today’s digital age, technology offers powerful tools that can significantly assist you in managing your investments and aiming for a 7% annual return.
- Robo-Advisors: These automated platforms use algorithms to manage your portfolio based on your risk tolerance and financial goals. They offer low-cost diversification, automatic rebalancing, and often tax-loss harvesting, making them an excellent option for hands-off investors looking for consistent returns.
- Investment Apps and Platforms: User-friendly apps provide access to a wide range of investment vehicles, real-time market data, research tools, and educational resources. They empower investors to take control of their portfolios and make informed decisions.
- Financial Planning Software: Tools that help you track your net worth, analyze your spending, and project your financial future can be invaluable. They can help you visualize the impact of different investment scenarios on your ability to achieve a 7% annual return and adjust your savings or investment contributions accordingly.
- Data Analytics and AI: While more advanced, some platforms use AI and machine learning to identify trends, predict market movements, and even suggest personalized investment strategies. While these tools should be used with caution and not as a sole basis for decisions, they can provide valuable insights.
Embracing these technological advancements can streamline your investment process, enhance your decision-making, and ultimately contribute to your success in achieving a consistent 7% annual return.
Long-Term Perspective and Patience for a 7% Annual Return
Achieving a 7% annual return is a marathon, not a sprint. It requires a long-term perspective and a significant amount of patience. Market fluctuations are inevitable. There will be periods of strong growth and periods of downturns. Emotional reactions to short-term market movements are often detrimental to long-term success.
The power of compounding is your greatest ally. Even modest returns, compounded over many years, can lead to substantial wealth accumulation. For example, consistently achieving a 7% annual return on an initial investment of $10,000 for 30 years would grow it to over $76,000, assuming no additional contributions. With regular contributions, the growth is even more dramatic.
Resist the urge to constantly check your portfolio or make frequent changes based on daily news cycles. Stick to your well-researched investment plan, rebalance periodically, and trust in the long-term growth potential of diversified assets. Patience, discipline, and a focus on your long-term goal of a 7% annual return will ultimately be rewarded.
Conclusion: Your Path to a 7% Annual Return
Achieving a consistent 7% annual return on your investments in today’s economic climate is a challenging yet attainable goal. It demands a strategic approach that encompasses a deep understanding of market dynamics, disciplined risk management, and intelligent asset allocation. By diversifying your portfolio across various asset classes, leveraging appropriate investment vehicles like ETFs, dividend stocks, and real estate, and consistently rebalancing, you lay a strong foundation for success.
Furthermore, managing behavioral biases, embracing technological tools, and maintaining a long-term perspective are equally crucial. The financial landscape is ever-evolving, requiring continuous learning and adaptability. By staying informed, making data-driven decisions, and adhering to a well-defined investment strategy, you can confidently navigate market complexities and steadily work towards your objective of a robust 7% annual return, securing your financial future.
Remember, while this guide provides comprehensive strategies, consulting with a qualified financial advisor can offer personalized insights and help tailor a plan that specifically addresses your unique financial situation and goals. Your journey to a 7% annual return is a personal one, and with the right knowledge and discipline, it is well within reach.
Author