As the leaves begin to fall and the holiday season approaches, another critical period for millions of Americans is underway: the 2026 ACA Open Enrollment Period. This annual window is your opportunity to secure essential health insurance coverage for the upcoming year, ensuring peace of mind and access to vital medical services. For many, navigating the complexities of health insurance can feel daunting, but understanding the key dates, your options, and the available financial assistance can make all the difference. The most crucial date to remember? December 15th. Missing this deadline could mean a gap in your coverage or being unable to enroll until the next open enrollment period, unless you qualify for a Special Enrollment Period.
The Affordable Care Act (ACA), often referred to as Obamacare, revolutionized the healthcare landscape by making health insurance more accessible and affordable for millions. It established Health Insurance Marketplaces (also known as Exchanges) where individuals and families can shop for plans, compare benefits, and receive financial assistance to help cover the costs. This article will serve as your comprehensive guide to the 2026 ACA Open Enrollment Period, detailing everything you need to know to make informed decisions about your healthcare future.
Understanding the 2026 ACA Open Enrollment Period: Why It Matters
The ACA Open Enrollment Period is the designated time each year when individuals and families can enroll in a new health insurance plan or change their existing plan through the Health Insurance Marketplace. This period is critical because, outside of it, you generally cannot purchase health insurance unless you experience a qualifying life event (QLE) that triggers a Special Enrollment Period (SEP). QLEs include things like getting married, having a baby, losing other health coverage, or moving to a new state.
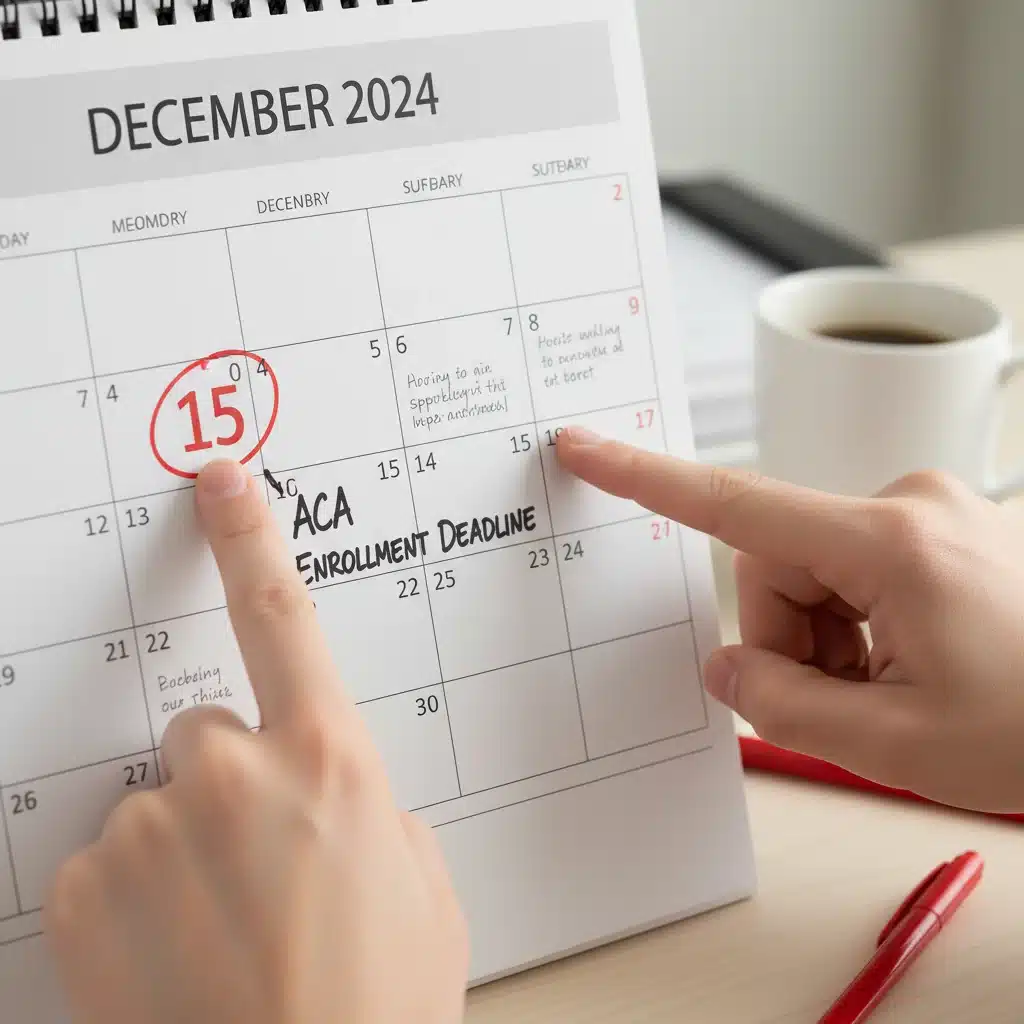
For the 2026 plan year, the Open Enrollment Period typically runs from November 1, 2025, to January 15, 2026. However, to ensure your coverage begins on January 1, 2026, you must enroll and select a plan by December 15, 2025. This early deadline is crucial for seamless coverage transition. If you enroll between December 16th and January 15th, your coverage will likely start on February 1, 2026, or even later, depending on your state’s specific rules.
Key Dates for the 2026 ACA Open Enrollment Period:
- November 1, 2025: Open Enrollment begins. This is when you can start browsing plans, comparing options, and submitting your application.
- December 15, 2025: This is the most important deadline. Enroll by this date for coverage to begin on January 1, 2026.
- January 15, 2026: Open Enrollment ends. If you enroll between December 16, 2025, and January 15, 2026, your coverage will typically start on February 1, 2026, or later.
Understanding these dates is the first step towards securing your health. The 2026 ACA Open Enrollment Period provides a vital opportunity to assess your healthcare needs and find a plan that fits your budget and lifestyle. Don’t underestimate the importance of timely enrollment; a lapse in coverage can lead to significant financial burdens if unexpected medical needs arise.
Who Should Enroll or Re-enroll During the 2026 ACA Open Enrollment Period?
Many people benefit from the ACA Open Enrollment Period. Here’s a breakdown of who should pay close attention:
- Individuals without health insurance: If you currently lack health coverage, this is your primary opportunity to enroll. Having health insurance protects you from high medical costs and ensures access to necessary care.
- Those with existing Marketplace plans: Even if you are happy with your current plan, it’s highly recommended to re-evaluate your options each year. Plans, premiums, and benefits can change, and new, more suitable plans might become available. Your financial assistance (subsidies) also needs to be re-calculated annually based on your updated income.
- Individuals seeking more affordable options: Many people may be paying too much for their current coverage or might qualify for new or increased subsidies. The 2026 ACA Open Enrollment Period is the time to explore these possibilities.
- People whose circumstances have changed: If your income has changed, you’ve moved, or your healthcare needs have evolved, you might find a different plan that better suits your current situation.
- Anyone considering COBRA: While COBRA can provide temporary coverage after leaving a job, it’s often very expensive. Marketplace plans, especially with subsidies, can be a much more affordable alternative.
The goal of the 2026 ACA Open Enrollment Period is to ensure that everyone has access to quality, affordable health insurance. Taking the time to review your options can lead to significant savings and better coverage.
Navigating the Health Insurance Marketplace: Your Options
The Health Insurance Marketplace is an online platform where you can compare and purchase health insurance plans. When you visit Healthcare.gov (or your state’s marketplace if your state runs its own), you’ll be guided through a process to:
- Enter your personal information: This includes details about your household size, income, and location. This information is crucial for determining your eligibility for financial assistance.
- Browse available plans: The Marketplace will show you all the plans offered in your area, categorized by metal tiers: Bronze, Silver, Gold, and Platinum.
- Compare plans: You can compare plans side-by-side based on premiums, deductibles, out-of-pocket maximums, co-pays, and covered benefits.
- Apply for financial assistance: Based on your income, you may qualify for premium tax credits (subsidies) that lower your monthly premium, and/or cost-sharing reductions (CSRs) that reduce your out-of-pocket costs.
- Enroll in a plan: Once you’ve chosen a plan, you can complete the enrollment process directly through the Marketplace.
Understanding Metal Tiers:
- Bronze plans: Offer the lowest monthly premiums but have the highest deductibles and out-of-pocket costs. They cover approximately 60% of healthcare costs. Best for those who anticipate minimal medical needs.
- Silver plans: Moderate monthly premiums and deductibles. They cover approximately 70% of healthcare costs. These plans are particularly important because if you qualify for cost-sharing reductions (CSRs), they are only available with Silver plans, making them significantly more valuable for eligible individuals.
- Gold plans: Higher monthly premiums but lower deductibles and out-of-pocket costs. They cover approximately 80% of healthcare costs. Suitable for those who expect to use medical services frequently.
- Platinum plans: The highest monthly premiums but the lowest deductibles and out-of-pocket costs. They cover approximately 90% of healthcare costs. Ideal for individuals with extensive medical needs.
Choosing the right metal tier depends on your anticipated healthcare usage and financial situation. Don’t just look at the premium; consider the total out-of-pocket costs, including deductibles and co-pays, especially if you have chronic conditions or expect to need significant medical care.
Financial Assistance: Making Healthcare Affordable
One of the most significant benefits of the ACA is the financial assistance available to help people afford health insurance. During the 2026 ACA Open Enrollment Period, you can apply for two main types of assistance:
1. Premium Tax Credits (Subsidies)
These credits lower your monthly health insurance premium. Eligibility is based on your household income relative to the federal poverty level (FPL). Thanks to recent legislation, more people qualify for larger subsidies, making healthcare more affordable than ever before. You can qualify for premium tax credits if your household income is between 100% and 400% of the FPL, and in some cases, even above 400% if your premium costs exceed a certain percentage of your income.
2. Cost-Sharing Reductions (CSRs)
CSRs help reduce the amount you have to pay out-of-pocket for deductibles, co-payments, and co-insurance. You must enroll in a Silver plan to receive CSRs, and eligibility is based on your household income being between 100% and 250% of the FPL. CSRs can significantly lower your total healthcare costs, making Silver plans a very attractive option for those who qualify.
It’s crucial to accurately report your income when applying through the Marketplace, as this directly impacts the amount of financial assistance you receive. If your income changes during the year, update your information on the Marketplace to avoid issues at tax time.
Preparing for the 2026 ACA Open Enrollment Period
To ensure a smooth enrollment process, gather the following information before November 1st:
- Household income: This includes wages, salaries, self-employment income, Social Security benefits, unemployment benefits, and other sources of taxable income for all members of your household.
- Household size: The number of people in your tax household, including yourself, your spouse, and any dependents.
- Current health insurance information: If you have existing coverage, have details about your current plan, including policy numbers and provider information.
- Employer-sponsored coverage details: If you or a family member have access to job-based coverage, you’ll need information about that plan, even if you don’t intend to enroll in it.
- Social Security Numbers (SSNs): For all household members applying for coverage.
- Immigration documents: If applicable.
Having this information ready will streamline your application process and help you quickly determine your eligibility for financial assistance during the 2026 ACA Open Enrollment Period.
What to Consider When Choosing a Plan
Selecting the right health insurance plan during the 2026 ACA Open Enrollment Period involves more than just looking at the monthly premium. Here are key factors to consider:
1. Network of Doctors and Hospitals
Check if your preferred doctors, specialists, and hospitals are in the plan’s network. Out-of-network care can be significantly more expensive. Different plans (HMO, PPO, EPO, POS) have different rules regarding network access and referrals.
2. Prescription Drug Coverage
If you take regular medications, review the plan’s formulary (list of covered drugs) to ensure your prescriptions are included and understand their cost-sharing tiers. Some plans might have high co-pays for certain medications.
3. Deductibles, Co-pays, and Co-insurance
- Deductible: The amount you must pay out-of-pocket before your insurance begins to cover costs for most services.
- Co-pay: A fixed amount you pay for a covered healthcare service after you’ve paid your deductible (e.g., $20 for a doctor’s visit).
- Co-insurance: Your share of the cost of a covered healthcare service, calculated as a percentage (e.g., 20% of the bill) after you’ve met your deductible.
Understand how these costs will impact your total healthcare spending, especially if you anticipate frequent medical needs.
4. Out-of-Pocket Maximum
This is the most you’ll have to pay for covered services in a plan year. Once you reach this limit, your health plan pays 100% of the cost of covered benefits. A lower out-of-pocket maximum offers more financial protection in case of serious illness or injury.
5. Essential Health Benefits
All plans offered on the Marketplace must cover ten essential health benefits, including:
- Ambulatory patient services (outpatient care you get without being admitted to a hospital)
- Emergency services
- Hospitalization (like surgery and overnight stays)
- Maternity and newborn care (care before and after your baby is born)
- Mental health and substance use disorder services, including behavioral health treatment (this includes counseling and psychotherapy)
- Prescription drugs
- Rehabilitative and habilitative services and devices (services and devices to help people with injuries, disabilities, or chronic conditions gain or recover mental and physical skills)
- Laboratory services
- Preventive and wellness services and chronic disease management
- Pediatric services, including oral and vision care (but adult dental and vision coverage aren’t essential health benefits)
While all plans cover these, the extent of coverage and cost-sharing can vary.
6. Special Programs or Features
Some plans may offer additional benefits like telemedicine services, wellness programs, or gym memberships. Consider if these added features are valuable to you.
By carefully evaluating these factors during the 2026 ACA Open Enrollment Period, you can select a plan that provides comprehensive coverage and financial protection tailored to your specific needs.
Common Mistakes to Avoid During Open Enrollment
The 2026 ACA Open Enrollment Period is a critical time, and avoiding common pitfalls can save you time, money, and stress:
- Missing the December 15th Deadline: This is the most common mistake. Missing it means your coverage won’t start on January 1st, potentially leading to a gap in coverage.
- Not Re-evaluating Your Plan: Even if you like your current plan, don’t auto-renew without reviewing. Premiums, benefits, and networks can change annually. New plans might offer better value or more suitable coverage.
- Ignoring Subsidies: Many people qualify for financial assistance and don’t realize it. Always go through the application process to see if you’re eligible for premium tax credits or cost-sharing reductions.
- Underestimating Healthcare Needs: Choosing a high-deductible plan to save on premiums might backfire if you end up needing significant medical care. Be realistic about your potential healthcare usage.
- Not Checking Provider Networks: Ensure your preferred doctors, specialists, and hospitals are in-network for any new plan you consider.
- Only Focusing on Premiums: While important, the monthly premium is just one part of the total cost. Consider deductibles, co-pays, co-insurance, and the out-of-pocket maximum.
- Not Updating Income Information: If your income changes throughout the year, update it on the Marketplace. Failing to do so can result in owing money back to the IRS or receiving less assistance than you’re entitled to.
- Waiting Until the Last Minute: The Marketplace can experience high traffic as the deadline approaches. Enroll early to avoid technical glitches or last-minute rushes.
By being proactive and informed, you can make the most of the 2026 ACA Open Enrollment Period and secure the best possible health insurance for yourself and your family.
Resources and Assistance for Enrollment
You don’t have to navigate the 2026 ACA Open Enrollment Period alone. Several resources are available to help you:
- Healthcare.gov: The official federal Marketplace website is your primary resource for information, plan comparison, and enrollment.
- State Marketplaces: Some states operate their own health insurance marketplaces. If your state has its own, you’ll be redirected there from Healthcare.gov.
- Navigators and Assisters: These are trained and certified individuals who provide free, unbiased help with the application and enrollment process. They can explain your options, help you understand subsidies, and assist with plan selection. You can find local help through Healthcare.gov.
- Insurance Brokers/Agents: Licensed insurance professionals can also help you compare plans, including those on and off the Marketplace. They often receive commissions from insurance companies, so ensure they are transparent about their recommendations.
- Customer Service Hotlines: The Marketplace typically has a customer service hotline you can call for assistance with technical issues or questions about your application.
Utilizing these resources can simplify the enrollment process and ensure you make the most informed decision during the 2026 ACA Open Enrollment Period.
What Happens After You Enroll?
Once you’ve successfully enrolled in a plan during the 2026 ACA Open Enrollment Period, there are a few final steps:
- Pay Your First Premium: Your coverage generally won’t become active until you’ve paid your first monthly premium. Your insurance company will send you information on how to do this.
- Receive Your Insurance Card: Your insurance company will mail you an insurance card. Keep this card handy, as it contains important information like your policy number and contact details for your provider.
- Understand Your Plan Documents: Review your plan’s Summary of Benefits and Coverage (SBC) and other plan documents. These provide detailed information about what your plan covers, your costs, and how to access care.
- Utilize Preventive Care: Remember that all ACA-compliant plans cover a range of preventive services at no extra cost, including vaccinations, screenings, and wellness visits. Take advantage of these to maintain your health.
- Update Information as Needed: If your income, household size, or contact information changes during the year, update your Marketplace account immediately. This ensures your subsidies are accurate and you don’t face issues at tax time or with your coverage.
By following these steps, you can ensure a smooth transition into your new health coverage and confidently utilize your benefits throughout 2026.
The Long-Term Impact of the ACA
The Affordable Care Act has profoundly impacted the American healthcare system since its inception. Beyond just providing a framework for the ACA Open Enrollment Period, it has:
- Expanded Coverage: Millions of previously uninsured Americans gained health insurance coverage.
- Protected Against Discrimination: Insurance companies can no longer deny coverage or charge more based on pre-existing conditions.
- Eliminated Lifetime Limits: Plans cannot put a dollar limit on the amount of care you can receive in your lifetime.
- Covered Young Adults: Young adults can stay on their parents’ health insurance plans until age 26.
- Increased Transparency: The Marketplace provides a standardized way to compare plans, making it easier for consumers to understand their options.
- Focused on Prevention: Emphasized preventive care, leading to healthier outcomes and potentially lower long-term healthcare costs.
The 2026 ACA Open Enrollment Period continues this legacy, offering a crucial opportunity for individuals and families to participate in a system designed to make healthcare more equitable and accessible. Your participation helps strengthen this system and ensures your personal health security.
Conclusion: Don’t Miss the December 15th Deadline!
The 2026 ACA Open Enrollment Period is a vital time to take control of your health insurance needs. Whether you’re enrolling for the first time, renewing your current plan, or seeking more affordable or comprehensive coverage, the time to act is now. Mark your calendars for December 15, 2025, to ensure your coverage begins on January 1, 2026. Don’t let this critical deadline pass you by.
Take advantage of the financial assistance available, carefully compare your options, and choose a plan that provides the protection and peace of mind you deserve. Health insurance is not just a safety net; it’s an investment in your well-being and future. Secure your affordable healthcare coverage today!